

Bloomberg has expanded its electronic trading capabilities in Japanese government bonds (JGBs), creeping into a market currently dominated by Tradeweb with market-on-close (MOC) capabilities.
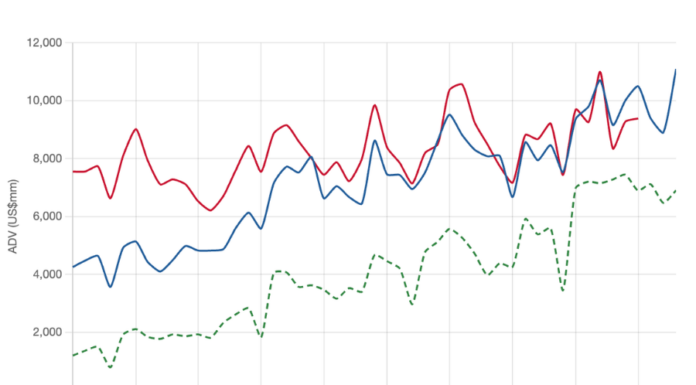
Electronic trading in JGBs has been steadily growing over recent years, with platforms introducing new solutions to the market.
READ MORE: Human battles machine in JGB market
Tradeweb is currently the most popular-trading platform, according to the region’s buy side. The latest to increase its offering is Bloomberg, which has expanded its MOC capabilities to cover JGBs.
“In my view, Tradeweb appears to remain the leading electronic trading platform for JGBs. That said, Bloomberg seems to have gradually gained some ground over the past year. Usage of Bloomberg at our firm has also increased steadily, albeit modestly,” Toshifumi Niwa, chief trader at Nippon Life Asset Management, told The DESK.
Bloomberg’s latest offering is the expansion of its MOC capabilities to cover JGBs.
MOC orders automatically execute a trade at, or close to, a session’s official closing price. This can help align trades with end-of-day price movements or index adjustments.
“While we have not yet used [the MOC functionality] at our firm, we are currently preparing to do so,” Niwa stated.
The service, accessible through Bloomberg’s fixed income execution management system (TSOX) is aligned with the market-at-close reference rate for JGBs (BB3P) and combines two existing Bloomberg functionalities: bid/offer list trading and trade automation tool Rule Builder.
This allows users to define execution criteria and automate order routing based on specific predefined conditions.
Bloomberg’s MOC capabilities were launched for European government bonds in 2024, and expanded to cover US Treasuries in 2025. Canadian government bonds and UK Gilts are also supported.
READ MORE: Bloomberg expands market-on-close list trading facility
Yields in 10-year JGBs have been growing at pace over recent months, spiking to 3.07%.

“Nevertheless, my impression is that liquidity in the interdealer market remains relatively thin. Conditions may be somewhat better on JGB auction days, but quote depth often remains limited and bid-offer spreads are not consistently tight,” Niwa observed.
Changes to JGB trading have been significant over the last year, with the potential of on-chain JGB collateral being explored by Mizuho, Nomura, the Japan Securities Clearing Corporation and Digital Asset in April.
READ MORE: Japan eyes on-chain JGB collateral
In August, MUFG launched a proof of concept for on-chain JGB repo transactions – a practice that has seen success in the US.
READ MORE: MUFG taps into tokenised govies
Niwa also predicts electronic trading developments beyond rates.
“While I certainly expect further development in electronic trading in the JGB market, I also see considerable potential for greater electronic execution in the Japanese yen credit market, including corporate bonds,” he said.
“My understanding is that the vast majority of transactions continue to be conducted by voice. This workflow creates a significant operational burden, so further electronification of the market would be very welcome from an operational-efficiency perspective.”
©Markets Media Europe 2026