

Despite the industry focus on automating every aspect of the trading process, some panelists at FILS Europe jumped to the defence of chat communications.
The fact that large elements of the workflow are still conducted manually – spreadsheets, emails and faxes being integral parts of the process – is a running joke in fixed income.
“Excel is still very much around. Emails, chat, they’re here to stay for sure,” affirmed Guillaume Carreno, managing director and global head of e-sales at Credit Agricole Corporate & Investment Bank. The latter remains pertinent; chats can provide key details that an automated system cannot.
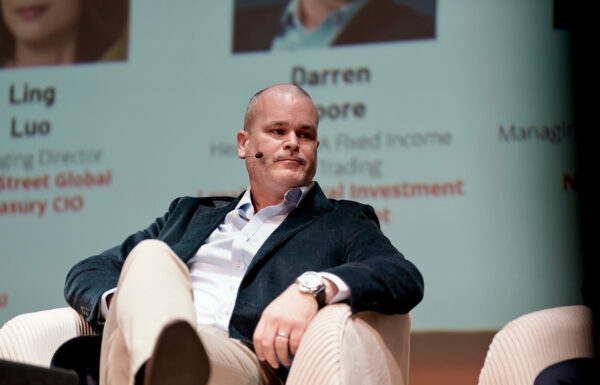
“A lot of our communications are verbal or through instant chat rooms,” confirmed Darren Moore, head of EMEA fixed income flow trading at Legal & General Asset Management.
“We have a lot of dialogue with portfolio managers and analysts before the trade even hits the order management system. [At LGIM] traders are pretty early on in the investment decision-making process.”
“What matters is the content in the messages, the sheer volume of information,” added Carreno. Some of that can be put into a structured form, but certain market colour and nuance may be lost.
“It’s hard to transmit that information through a GUI or an API, and it’s where you can add value,” agreed Olivier Dermaux, EMEA head of fixed income primary at S&P Global.
Carreno suggested that firms use an AI layer over their chats to extract and structure vital information, making it more readable and actionable.
A buy-side trader echoed this sentiment, musing that Ai could look at chat patterns and historical dealer interaction to provide more detailed and practical analytics.
On AI applications, Dermaux commented, “It is being used to analyse the data they get from primary, to predict what allocations they should receive on a syndicate deal, to score brokers.”
The sell side is embracing AI slightly faster than the buy side, he added.
“We don’t see much demand for AI in workflows on the buy side. They want to keep a manual hold on the order.”
Of course, some of the stickiness of chat communications is down to habit.
“People who have been in the market for a long time have always used live chats to communicate with banks in a primary space, and they don’t see the need to change that,” Dermaux said.
“Other times there’s a regional aspect. Without overgeneralising, there is a definite fixation for staying in chat in APAC. There’s an expectation of white-glove service from salespeople.”
There are spaces in the primary markets where automation can be – and has been – transformational. Tools such S&P Global’s IssueNet and IssueBook are key examples.
“IssueNet creates one version of the truth. People who worked on syndicate in the past will know that the consolidation process used to be made up of phone calls and Excel spreadsheets, which could take hours. It was all automated through that tool, which was a major step.”
The next hurdle is electrifying the buy side component, he continued.
“We now have all these use cases, and there ends up being 10 different apps across the desktop,” Carreno explained.
“Trying to collate them all into a single interface that actually makes sense, to give a holistic view of everything that’s happening, is the next issue.”
©Markets Media Europe 2026