

Automation and AI have been conference buzzwords for years, but the real use cases are now coming to light – and many are urging caution around the long-term effects.
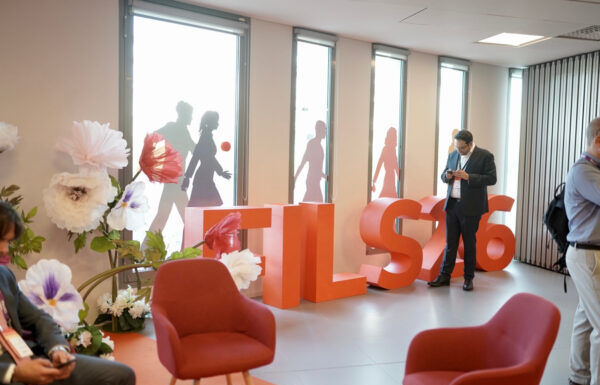
Speaking at FILS Europe, Stephanie Creswell, fixed income trader at Vanguard Asset Management, stated, “We bucket trades into three categories: high touch, low touch and no touch.”
“On the high-touch side it’s more idiosyncratic names, less liquid blocks. There, we would use a traditional, voice-negotiated method. On the low-touch side it’s more liquid names that you’d want to trade in a package, through a portfolio trade or an RFQ list. No-touch is auto-execution within a predefined set of parameters.”
“Historically for us, those last two methods would represent maybe 40% of the traded volumes on our desks. Now that number is more like 70%.”
The firm, which holds US$12.1 trillion in assets under management (AUM), is dominated by passive fund strategies.
Across the board, speakers agreed that automation is far more useful in rates than credit trading, and that it is better used for smaller trade sizes and liquid, transparent assets.
One buy-side trader stated that “automation has been a godsend,” helping them to free up time for more high-touch orders.
READ MORE: FILS USA 2026: Where does the industry stand in scaling AI and automation?
Not everyone is so ebullient in their praise. Another speaker raised the idea that automation can create serious issues for portfolio managers.
“It removes portfolio management from the market. You don’t need to discuss a trade with the street, you don’t necessarily need to go around and ask for different quotes, or why someone is acting differently, or what the mood around a particular bond is. Automation just stops that flow of information.”
Between the automation of small-ticket trades and the use of AI to streamline previously laborious practices, concerns were raised by the audience that a knowledge gap could be emerging between senior and junior traders. Use of these technologies could mean that individuals are missing a foundational understanding of markets, speakers suggested, and are unable to operate and find liquidity pockets in volatile, fast-moving environments.
On the subject of AI, one speaker was keen to stress that it is not a fix-all solution – despite what top-down pressure to apply the tech across all operations may suggest.
“No one is hitting buy or sell with AI. Don’t let AI make any decision that isn’t reversible,” one speaker advised.
Inés de Trémiolles, global head of trading at BNP Paribas Asset Management (€1.7 trillion AUM), was similarly cautious.
There is no real benefit applying AI for AI’s sake,” she said.
“We do a lot of things with AI – pre-trade, sometimes post-trade analysis – but not real execution. I think regulation has a big part of it. We need regulation to be there for us.”
READ MORE: FI at “beginner’s stage of execution automation”
According to de Trémiolles, automation at BNP Paribas AM is most advanced in Europe, where markets are more digital.
“You have to adapt to local markets. We deploy in Europe, then see the other regions where it can be beneficial.”
©Markets Media Europe 2026