

Corporates issued around $1 trillion of new debt in 2026, according to S&P Global iBoxx data, and rather than straining the secondary market the supply has coincided with tighter bid-ask spreads and higher trading volumes across most of the credit market, MarketAxess figures show.
Markets are awash with new debt, and the Bank for International Settlements warned in June that excessive borrowing could cause liquidity shocks. No-one seems to have told bond traders, however.
The borrowing has been driven by capital spending on artificial intelligence and defence. Sovereign issuance ran far higher still.
Its effect on the stock of tradeable paper is visible issuer by issuer. The chart below ranks the largest increases in corporate debt outstanding this year — the measure that matters for depth, since it counts what is left to trade after maturities.

Bets on AI are prominent, with Amazon, Alphabet and Meta dominating the chart, along with banks that are increasing their balance sheets to keep up.
The textbook consequence of supply on that scale is a secondary market under strain: new paper arriving faster than dealers can distribute it, concessions widening to clear it, and bid-ask spreads paying for the privilege. That is not what happened.
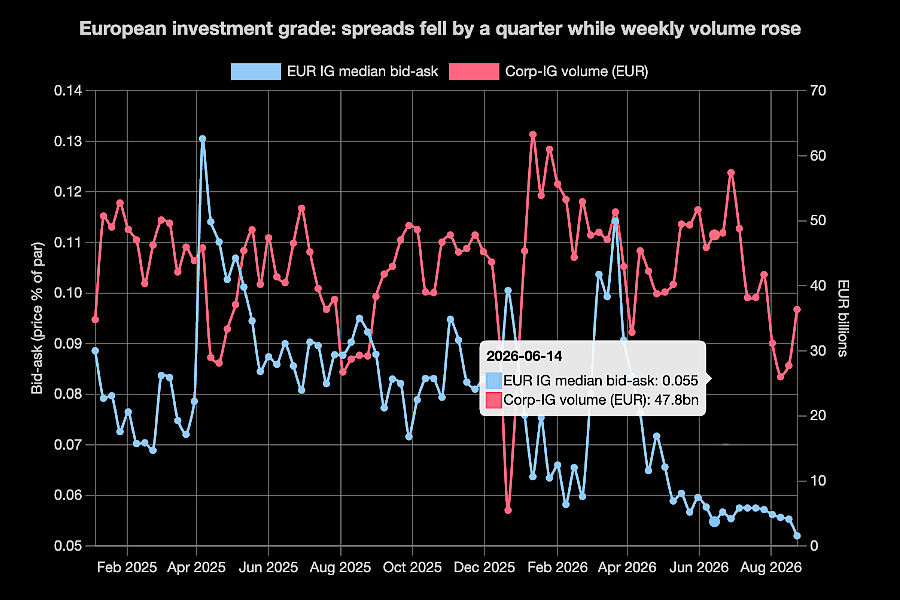
Comparing the 34 weeks to 23 August 2026 with the same weeks of 2025, which strips out seasonality, four of the five credit markets MarketAxess tracks are both cheaper to trade and busier than a year ago.
European investment grade shows it most clearly. Median bid-ask fell from 0.0879 to 0.0673 price % of par, a compression of 23.5%, while weekly volumes rose from €41.5bn to €45.4bn, up 9.5%. By August the spread comparison had widened to 39.0% tighter than the same weeks of 2025.
Loading…
Source: MarketAxess
Excluding the August lull and the holiday weeks altogether, euro investment grade volumes are still up 7.9% and spreads down 20.7%.
US investment grade tells the same story with heavier weights: volumes up 16.9% to $202.8bn a week, spreads 14.1% tighter. US high yield is up 6.9% on volume with spreads 23.3% tighter.
Loading…
Source: MarketAxess
Why the supply did not bite
Two mechanisms plausibly reconcile record issuance with cheaper execution. A new issue is a supply event on the day it prices, and the concession paid to place it is a cost. But once placed it becomes a line in the outstanding stock, tradeable for years. A market that absorbs $1 trillion ends the year with more instruments outstanding across more maturities and more issuers, which is the raw material of a deeper secondary market. New issues also trade heavily in their first months, lifting volumes directly.
The second is that the borrowers behind this wave are, in the main, large and highly rated. Supply concentrated in the most liquid part of the curve is easier to digest than the same volume spread across weaker credits.
The market that did not borrow, and did not improve
Emerging markets is the exception on both measures, which makes it the test of the argument.
It is the only market where bid-ask has not meaningfully improved: 0.1751 against 0.1800 across the matched weeks, a compression of 2.8% against euro investment grade’s 23.5%.
Loading…
Source: MarketAxess
Its volume advantage over last year has decayed quarter by quarter.
Across 2026 emerging markets has still done 11.1% more business than in 2025. A substantial advantage has been given back over six months, in the one market whose cost of execution never fell.
If the issuance argument holds, that is what it should look like. The AI and defence borrowing wave is a developed-market corporate phenomenon; emerging market corporates are not the ones funding data centres. A market that received little of the new supply shows little of the resulting depth.
Where the abundance stops
The improvement is an annual average. It does not describe how these markets behave when tested.
Across the four weeks from 1 March, US investment grade repriced sharply and went on transacting, while European investment grade repriced harder — 64% above its January average at the single-week peak — and volumes fell away. Average trade size in Europe fell 11%.
The prior-year data contains a second episode, President Trump’s tariff introduction in April 2025, with the same signature.
One interpretation is that euro investment grade absorbs a shock through price and through withdrawal, where dollar investment grade absorbs it through price alone. Abundant liquidity in the average week is not the same as liquidity in the week it is needed.
Loading…
Source: MarketAxess
Recovery separated the markets more than the shock did. Euro investment grade regained its pre-stress spread in four weeks, US high yield in six, US investment grade in eight and euro high yield in 13. Emerging markets took 14 and then widened again, and has been above its January level in 21 of the 22 weeks since the peak.
European high yield is the other exception, and the only market where volumes are lower on the matched weeks, at €6.1bn against €6.3bn. The shortfall has deepened through the year, from 1.0% in the first quarter to 9.6% in August.
For most of the credit market, a year of record supply has been a year in which execution got cheaper and there was more of it. Euro investment grade is trading at spreads 39% below last August on higher volumes. For desks that spent 2025 paying up for liquidity, the borrowing wave has been an unambiguous benefit.
©Markets Media Europe 2026