

By Ivy Wanta, Chief Product Officer, RealQ
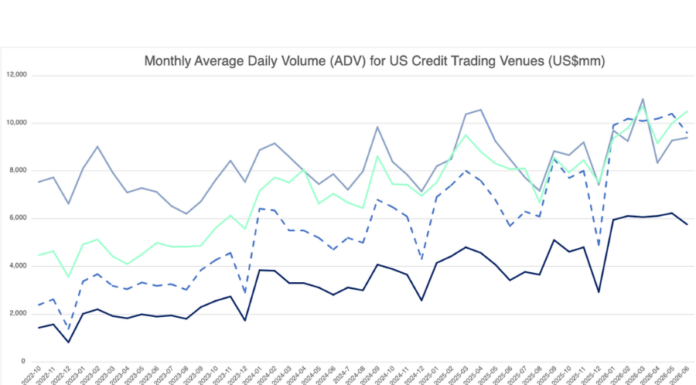
The slowdown in the growth of electronic trading across credit markets has been well documented. While smaller orders have electronified rapidly, a significant portion of the credit market remains dominated by voice: large, complex or discreet trades. Unlocking this segment is essential to the future proliferation of electronic trading.
Given the operational and efficiency gains that electronic trading offers, why has progress been so slow? A key hurdle to the proliferation of electronic trading may be unexpected: best execution. Trading firms’ best execution (Best Ex) obligations under MiFID II and FINRA serve an important purpose – obligating firms to deliver execution quality and formalizing how performance is assessed. However, while well-intentioned, the regulatory requirement has had unintended consequences – particularly in credit markets.
Central to best execution obligations is the requirement that brokers evidence that they have achieved best execution. However, given that a trader’s execution affects the market and there is no way to prove the outcome of a different approach, this is hard to definitively demonstrate. To meet these complex challenges, RFQs have become the catch-all tool of choice for credit traders seeking liquidity and meeting best execution requirements, despite being ill-suited to larger trades.
Adequate or ‘best’?
The RFQ has risen to prominence because it excels in auditability, providing a clear record of which dealers were approached and when, while promoting competitive pricing through dealer participation. This makes it an ideal protocol for checking a box in a best execution process, allowing a trader to say, “these were the prices offered and I picked the best one.”
However, RFQ is limited in both use and what it can reveal about true execution quality. RFQs are associated with significant pre- and post-trade information leakage, which means that they are not fit for purpose beyond a certain liquidity profile. And if a trader tries to break up a larger trade into smaller chunks using RFQ, there is associated market impact over the course of the larger trade that is not captured.
This information leakage is a problem. The risk of signaling a position or intent to the broader market influences the trading behavior of participants who do not want to show their hand. It has therefore meant that these larger, more sensitive trades – with the potential to move markets or give an insight into a trading strategy – have largely been executed by voice between trusted counterparties.
This reliance on voice to execute more complex trades has created a data vacuum. Limiting interactions to a handful of trusted counterparties may do just enough to satisfy Best Ex requirements. However, it can become a barrier to achieving true best execution by restricting liquidity to a trader’s immediate network. It can also force traders to divide larger trades and default to RFQ, risking higher execution costs and market impact.
Reliance on RFQ is a product of the current trading and regulatory environment. To encourage participants to trade large orders electronically, traders must have confidence that any information they share is subject to clear rules around data ownership, confidentiality, permitted use and redistribution. By prioritising data governance in a secure electronic trading environment, participants can share trading intent more broadly, expanding access to liquidity while reducing concerns around information leakage and supporting better execution outcomes.
Trust, and the alignment of incentives, underpins market evolution
The focus on Best Ex, or being able to demonstrate a consistent price comparison process, has led to the adoption of protocols that, for many, trading circumstances are better at meeting Best Ex obligations than achieving true ‘best execution’. This has led to trading behavior that limits electronification for larger trades and disincentivizes dealer participation in these orders.
There is a better way of electronifying larger, more complex trades and achieving Best Ex. This is by creating a trusted environment in which dealers and buy-side clients can share trading intentions with limited information leakage, match high-quality liquidity at size and reduce market impact, and thus trade on even more competitive prices and sizes. Best Ex processes then must evolve to acknowledge that sourcing high-quality liquidity in this way may improve overall execution quality relative to the process of comparing multiple quotes.
The best does not have to be the enemy of the good. A more flexible, workflow-agnostic approach to best execution would help close the gap between proving execution quality and actually achieving it. Credit markets have evolved significantly, but market structure and execution frameworks have not always kept pace. If electronification is to reach the next stage of growth, both must evolve together.
©Markets Media Europe 2026